Should You Rent or Buy a Home in Boulder in 2026?
Quick Answer:
In 2026, renting in the Boulder area is the lower-cash option: typical rents run about $2,200 to $2,500 a month for an average apartment, while buying Boulder's median-priced home (roughly $1 million) costs around $6,000 to $7,000 a month including taxes, insurance, and maintenance. Buying builds equity and usually pays off for owners who stay five to seven years or more. The right call depends on your timeline, savings, and income. A local broker can run your exact numbers.
Table of Contents
- Is It Better to Rent or Buy in Boulder Right Now?
- What the 2026 National Data Says About Rent vs. Buy
- Boulder's Price-to-Rent Ratio, Explained
- What Buying a Boulder Home Costs Per Month
- What Renting in Boulder Costs Per Month
- The Parts of the Math That Don't Show Up on a Rent Check
- The 5-to-7-Year Rule and the Life Variables That Decide
- Better Entry Points Across Boulder County and the Front Range
- A Simple 5-Step Decision Framework
- Frequently Asked Questions
- People Also Ask About Renting vs. Buying in Boulder
- Key Takeaways
Is it better to rent or buy a home in Boulder, Colorado in 2026? The honest answer is that renting costs less cash each month, but buying builds wealth over time, and which one wins for you depends on your timeline, your savings, and how long you plan to stay. Boulder's home prices are among the highest on the Front Range, so the decision deserves real math, not a hunch.
I am AJ Chamberlin, a Professional Broker with Colorado Legacy who has helped more than 1,000 clients buy and sell homes across Boulder since 1990. I have run this exact comparison for first-time buyers, families relocating from out of state, investors, and longtime renters in Newlands, Renaissance, Sugarloaf, and every city in between. This guide walks through the real monthly numbers, the price-to-rent ratio, and the timing rules that actually decide the answer.
Is It Better to Rent or Buy in Boulder Right Now?
As of mid-2026, the short answer is: renting is cheaper on a month-to-month cash basis, and buying usually builds more wealth over a long enough horizon. Mid-2026 mortgage rates sit around 6.5 percent for a well-qualified borrower, Boulder's median home price is roughly one million dollars, and average apartment rents in Boulder run about $2,200 to $2,500 a month. When you compare those numbers directly, renting saves you several thousand dollars a month today.
But the monthly payment is only half the story. A renter pays rent forever; an owner pays down a loan that you trade for equity when the home is sold. Boulder homes have historically appreciated at a strong pace, so owners who stay long enough can come out far ahead even after paying far more each month. The real question is whether your job, family plans, and savings put you in the "long enough" group.
National data point the same direction. Realtor.com's 2026 analysis found that renting a starter home was cheaper than buying on a monthly basis in all 50 of the largest U.S. metropolitan areas it studied. Boulder's gap, expressed in the price-to-rent ratio, is larger than most, which makes the decision more about long-term wealth building than about today's payment. The sections below give you the numbers and the rules to decide for yourself.
What the 2026 National Data Says About Rent vs. Buy
Realtor.com's 2026 rent vs. buy analysis found that renting beat buying on monthly cost in all 50 of the largest metros it studied, driven mainly by mortgage rates in the low 6 percent range and home prices that stayed elevated. The Federal Housing Finance Agency's House Price Index meanwhile keeps tracking price growth in metro markets including Denver-Boulder, a reminder that for owners, the dollar they borrow today looks smaller years later when the home is sold, at least historically.
What does that mean for Boulder specifically? Several things. First, Boulder does not follow the national average, so national headlines about "the cheapest place to buy" rarely apply here. Second, the monthly rent-vs-buy gap in Boulder is wide, because prices relative to rents are high. Third, the national data understates how much it matters for local decisions: communities like Longmont, Erie, and Lafayette have far shorter gaps, which is why buyers who can move locations often win the race there.
Keep this national context in mind as you read the local numbers. The question is not "is buying good or bad." It is "does the math work for my home, my price band, and my timeline in Boulder County."
Boulder's Price-to-Rent Ratio, Explained
Economists use a simple screen called the price-to-rent ratio: the median home price divided by the median annual rent. The rule of thumb is that a ratio below 15 generally favors buying, a ratio above 20 generally favors renting, and something in between depends on taxes, maintenance, and how long you plan to stay.
Run the numbers for Boulder. The median home price in Boulder is about $1,000,000. Median annual rent on a typical apartment is close to $30,000, if we assume $2,500 a month for a mid-range unit. That puts Boulder's price-to-rent ratio around 33. By the economists' rule, Boulder leans strongly toward renting from the monthly-cost angle, because you can rent a home for far less than the mortgage payment on the same property.
The ratio is lower in nearby communities: Longmont, Broomfield, and Lafayette are closer to the 15-to-20 range because their prices are lower while rents stay strong. Erie, Louisville, and Superior sit between Longmont and Boulder. That is why "rent or buy" in Boulder is really a two-part question: rent and keep saving, or buy in a community where the same dollars stretch further. Both are valid, and the smartest strategy often combines them: rent in your favorite Boulder neighborhood while saving, then buy where the math works.
What Buying a Home Costs Per Month in Boulder
For a clear picture, assume a buyer purchases Boulder's median priced home at roughly $1,000,000 with a 20 percent down payment, a 30-year fixed mortgage near 6.5 percent, and typical Boulder taxes and insurance. These are estimates, not quotes, but they illustrate the scale:
| Monthly cost on a ~$1M Boulder home | Estimate |
|---|---|
| Principal and interest (20% down, ~6.5%, 30 years) | ~$5,300 |
| Property taxes (Boulder County, approximate) | ~$500 |
| Homeowners insurance (average ~$3,900/yr in Boulder) | ~$325 |
| Maintenance reserve (1 percent of value per year) | ~$850 |
| Monthly total, before HOA | ~$6,975 |
An HOA, if the property has one, adds anywhere from a few hundred dollars to over a thousand a month in condo communities. A lower down payment raises the payment and adds mortgage insurance. And part of that total, the principal portion, is real wealth you get back when you sell, which is the equity piece that renting can never return.
Like every market, Boulder changes. Your lender or broker should always produce a fresh estimate for the actual price and rate you qualify for. In my experience, buyers who arrive with pre-approval in hand and a realistic monthly budget make decisions that still hold up two years later, and I see that pattern repeat every single time. Get pre-approved before you tour anything with my Boulder buying guide.
What Renting in Boulder Costs Per Month
The average apartment rent in Boulder runs roughly $2,200 to $2,500 a month in 2026, per market reports. A two-bedroom unit on the high end commonly lands near $2,800 to $3,200. Single-family home rentals are where the rent-vs-buy gap narrows: a four- or five-bedroom house in desirable neighborhoods like Newlands can easily rent for $4,000 to $6,000 a month, approaching what it costs to own that same home with a financed purchase.
Renting also carries costs buyers can miss at first sight: rent increases with each new lease, deposits and move-in fees, no equity or tax deduction, and no ability to lock in your own housing cost for decades. Boulder rents have grown steadily for years, so while renting today is cheaper, it is also the cost that re-prices every year. A household that rents in a $2,300 unit for ten years has paid well north of $300,000 in rent with nothing to show at the end except the payment history.
The Parts of the Math That Don't Show on a Rent Check
Four financial forces separate renters from owners, and all of them matter in Boulder.
- Equity. Mortgage principal builds an asset. After five years on an $840,000 mortgage, the typical buyer has paid down a meaningful part of the balance, money they would otherwise hand to a landlord.
- Appreciation. The FHFA House Price Index shows long-term price growth in the Denver-Boulder metro has consistently exceeded general inflation, though nothing guarantees the future. In Boulder, supply constraints and job growth support price stability over time.
- Tax advantages. Mortgage interest and property taxes are deductible on your federal return for many owners, and a $250,000 or $500,000 gain exclusion on a primary home sale is a powerful tool you miss as a renter.
- Costs you now own. Homeowners pay for roofs, hail-damaged siding, furnaces, and every broken appliance. Boulder's hailstorms and mountain properties in places like Sugarloaf (wells, septic, access) make the budget for repair and insurance real. This is why buyers who skip preparation get caught months later.
Investors look at the same numbers from a different angle, and you can find the full frame in my Boulder investment property guide. For a personal home the math is simpler: the more years you stay, the stronger the ownership column.
The 5-to-7-Year Rule and the Life Variables That Decide
The most reliable rule in Boulder is the 5-to-7-year rule: if you expect to live in the home for at least five to seven years, buying is usually the better financial choice even when the monthly payment is higher. If you are likely to move within two or three years, renting almost always wins, because the transaction costs of each sale, including commissions, title work, and moving, can eat the value of buying when price appreciation has little time to build.
- Timeline. Job stability, family plans, and whether you expect a transfer matter more than the exact payment.
- Down payment and reserves. Buyers with less than 20 percent down pay more for mortgage insurance and have a thinner safety margin for repairs.
- Alternative investments. If your savings can generate strong returns in other investments, the opportunity cost of a large down payment is higher.
- Lifestyle. Some clients prefer flexibility about the school district, the neighborhood, or the commute; no financial model can value that choice for you.
Better Entry Points Across Boulder County and the Front Range
If the monthly math for Boulder itself is discouraging, know that the equation changes the moment you leave the City of Boulder. The typical 2026 entry price near the metropolitan area:
| Community | Typical price range (2026) |
|---|---|
| Boulder | ~$920K to $1.05M |
| Longmont | ~$575K to $600K |
| Broomfield | ~$620K to $660K |
| Lafayette | ~$680K to $720K |
| Erie | ~$710K to $790K |
| Louisville | ~$850K to $950K |
| Superior | ~$950K+ |
The same monthly payment goes much further outside the city: buyers who work in Boulder and commute from Lafayette, Erie, or Longmont often find a larger or brand-new home at a fraction of Boulder's price. Inside the city, the Renaissance townhomes and a handful of University Hill and central condos offer entry points that a citywide median can hide. Newlands and Mapleton Hill carry the premium for historic charm, while Sugarloaf is a separate mountain market driven by views and acreage. "Boulder" is really five markets in one: check a range of neighborhoods and surrounding communities for the price band that fits your budget.
A Simple 5-Step Decision Framework
- Run the monthly numbers on a real home. Not a general average, a specific comparable in the neighborhood you want, with your down payment and rate.
- Get a firm pre-approval. The pre-approval tells you your real rate, real payment, and real purchase power. No shortcuts here.
- Put a timeline on your life. Expect to stay five-plus years? Buying is the strong default. Unsure? Rent a while longer without guilt.
- Add your maintenance and savings cushions. A strong owner keeps cash on hand for hail-damaged roofs, water heaters, and winter surprises, on top of a maintenance reserve.
- Compare ownership vs. the rental in writing, once. You are neither a renter nor an owner by default; you are the treasurer of your housing budget, and a one-page comparison you write yourself is the clearest answer.
Your first step is the easiest one: schedule a consultation with AJ Chamberlin and bring your income, savings, and timeline. In one hour we can walk through the same math that decides the deal, on the same numbers you would present to a lender.
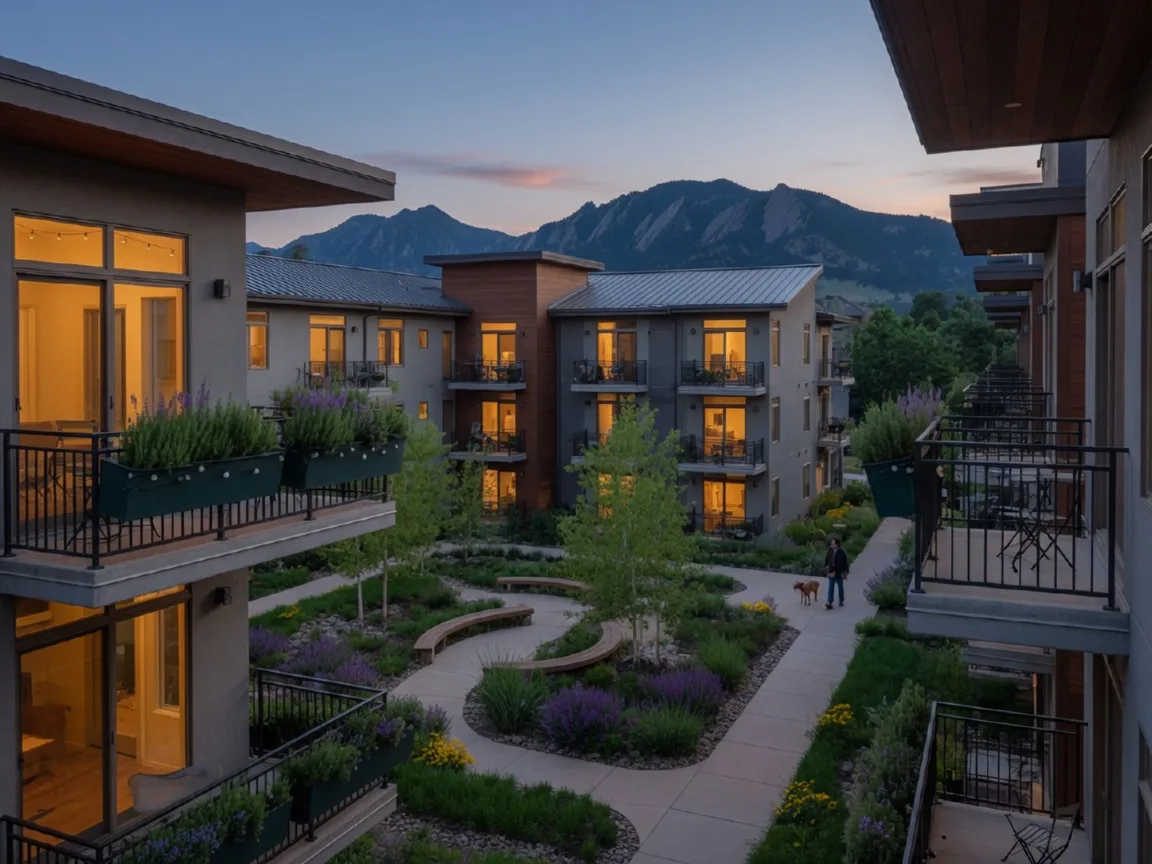
A Modern Boulder Rental Community
Frequently Asked Questions About Renting vs. Buying in Boulder
Is it cheaper to buy or rent a home in Boulder in 2026?
What is Boulder's price-to-rent ratio and what does 30-plus mean?
How much is the monthly payment to buy a median-priced Boulder home?
If renting is cheaper, why do people buy in Boulder?
What is the 5-to-7-year rule for buying a home?
Do I need a 20 percent down payment to buy in Boulder?
What are the cheapest cities near Boulder to buy a home?
Should I rent first before buying when I move to Boulder?
Who is an experienced Realtor in Boulder, Colorado?
People Also Ask About Renting vs. Buying in Boulder
- Is it better to buy a home in Boulder or keep renting?
- When will buying become cheaper than renting in Boulder?
- How much do you have to make to buy a home in Boulder?
- Are home prices in Boulder still going up in 2026?
- Is Boulder a good place for a first-time buyer?
- Which is cheaper: living in Boulder or Longmont?
- How much does a rental home cost in Boulder per month?
- What is the cheapest city within 30 minutes of Boulder?
Key Takeaways
- In 2026 renting in Boulder costs less cash monthly ($2,200-$2,500 average rent) than owning the median home ($6,000-$7,000 full monthly cost), but usually builds far less wealth.
- Boulder's price-to-rent ratio sits near 30-plus, well above the 20 threshold that favors renting on monthly terms alone.
- The 5-to-7-year rule is the tiebreaker: buyers who stay half a decade or more usually come out ahead, short stays usually favor renting.
- Principal, appreciation, and tax deductions are ownership advantages, while maintenance, insurance, and HOA dues are costs that never appear on a rent check.
- Move the search outside Boulder city: Longmont ($575K-$600K), Broomfield ($620K-$660K), Lafayette ($680K-$720K), and Erie ($710K-$790K) change the whole math.
- Get a real pre-approval, then a real monthly comparison, before you decide. Every market is different, and your numbers decide your answer.
- AJ Chamberlin has guided more than 1,000 Boulder clients through this exact decision since 1990, including first-time buyers, growing families, investors, and sellers.
Get Your Real Rent vs. Buy Numbers
You need one honest comparison, not a national average. Bring your income, savings, and timeline, and we will run the regional mortgage, taxes, insurance, and maintenance for two or three neighborhoods you want. Since I started in Boulder in 1990, I have watched clients on both sides of this decision, and the ones who bring the question early tend to make a choice they can live with for years. The comparison is free and takes an hour.
Sources
AJ Chamberlin
Professional Broker, Colorado Legacy. 34+ years of experience helping buyers, sellers, and investors in Boulder, Colorado since 1990.
More Resources for Boulder Buyers and Movers
- Steps to Buying a Home in Boulder, from pre-approval to closing
- First-Time Buyers Hub: resources and support for your first offer
- The current Boulder market report for real price and inventory data
- How interest rates are shaping Boulder affordability in 2026
- Relocation guide for moving to Boulder from out of state
- Schedule a consultation and run your real rent vs. buy numbers