How Escrow Works in Colorado: A Step-by-Step Guide for Boulder Buyers and Sellers
Quick Answer
Escrow is the period between an accepted offer and closing day, and in Colorado the title company runs it as a neutral third party. For financed purchases it typically lasts 30 to 45 days: contract and earnest money first, then title work, inspections, and appraisal, the Closing Disclosure 3-day review, the final walkthrough, and finally signing, funding, and recording.
Table of Contents
- 1. What Is Escrow, and Who Runs It in Colorado?
- 2. How Long Does Escrow Take in Colorado?
- 3. Step 1: Offer Accepted, Earnest Money Deposited
- 4. Step 2: Title Search, Commitment, and Title Insurance
- 5. Step 3: Inspections, Appraisal, and Contingency Windows
- 6. Step 4: The Closing Disclosure and the 3-Day Rule
- 7. Step 5: The Final Walkthrough
- 8. Step 6: Signing Day at the Title Company
- 9. Step 7: Funding, Recording, and Getting the Keys
- 10. Escrow and Closing Across Boulder's Communities
- 11. Frequently Asked Questions
- 12. Key Takeaways
What Is Escrow, and Who Runs It in Colorado?
Escrow has two meanings, and both apply to a home purchase. In the narrow sense, escrow is a neutral arrangement where money and documents are held by a third party until every condition of the contract is met. In the everyday sense, "escrow" is the whole period between the day your offer is accepted and the day the sale closes: usually the busiest three to six weeks of the transaction.
Colorado is what real estate professionals call a "title company state." Instead of a lawyer or a government office running the closing, a licensed title company acts as the neutral escrow agent. It holds the earnest money in a trust account, orders the title search, issues the title commitment, coordinates the settlement statement, handles the signing, collects and disburses funds, and records the deed once the sale is complete. The title company works for both parties equally, which is why it is the right address for questions about where a document or a deposit stands.
Closing is the final event of escrow: the day the buyer signs the loan documents, the seller signs the deed, the lender wires the funds, the deed is recorded with the county, and the keys change hands. Everything before that day is the process that makes the handoff clean. In more than three decades guiding buyers and sellers through Boulder-area closings, I have watched the process run smoothly in as little as a few weeks and seen it stretch into months, and the difference is almost never luck. It is preparation, documentation, and a calendar that everyone respects.
How Long Does Escrow Take in Colorado?
Plan on 30 to 45 days for a financed purchase in Colorado, which is the standard range for a Boulder-area contract with a mortgage. Cash purchases can close in 7 to 21 days when the title is clean and the parties are responsive, because there is no lender, no appraisal, and no Closing Disclosure clock. The table below shows typical timelines and what drives them.
| Transaction Type | Typical Timeline | What Sets the Pace |
|---|---|---|
| Financed purchase | 30 to 45 days | Appraisal scheduling, underwriting, the Closing Disclosure 3-day review, and lender capacity around month-end. |
| Cash purchase | 7 to 21 days | Title search speed, HOA document turnaround, survey or inspection pace, and how fast the parties sign. |
| New construction | Tied to completion, often longer | The builder sets the closing date; the contract opens a closing window after completion and the certificate of occupancy. |
| Mountain and rural property | Often 45 to 60 days | Well, septic, and access due diligence, plus survey and fire mitigation confirmations for homes like those in Sugarloaf. |
Whatever the timeline, the structure is the same. Colorado's standard purchase contract, the form approved by the Colorado Real Estate Commission, sets the dates for earnest money, inspection objections, loan commitment, and closing. Each deadline that passes without action usually means an automatic extension or a waived contingency, so the contract calendar is the real master schedule.
Step 1: Offer Accepted, Earnest Money Deposited
The moment both parties sign the purchase contract, the clock starts. The buyer then deposits earnest money, commonly 1 to 3 percent of the purchase price in Boulder-area deals, and often at the higher end in competitive situations. This deposit is not a fee; it is a good-faith signal that the buyer intends to perform, and it is credited back to the buyer at closing.
In Colorado, earnest money is held in a neutral trust or escrow account, typically with the title company or the listing broker's escrow account, and never paid directly to the seller. It stays there through the contingency period. If the buyer backs out within the terms of the contract, such as failing an inspection contingency, the deposit is returned. If the buyer defaults without a protected reason, the seller may be entitled to the earnest money under the contract's terms. Because the stakes are real, your agent should confirm in writing where the deposit will sit and what the contract's release language says before you wire a dollar.
Step 2: Title Search, Commitment, and Title Insurance
Within the first week or two, the title company examines the property's chain of title. In Boulder County, that means digging through decades of recorded deeds, liens, easements, and court filings to confirm the seller actually owns the property free of surprises. The result is the title commitment: a document that lists the conditions the title company must clear or insure before it will close the deal. Common items include outstanding mortgages being paid off at closing, tax liens, easements that cross the lot, and the occasional judgment lien from a name that matches the seller's.
Title insurance protects against defects a search cannot see, such as forged documents, missing heirs, or recording errors. Most Boulder buyers carry a lender's policy, which protects the mortgage lender, and many also buy an owner's policy, which protects the buyer's ownership rights. In Colorado, the seller typically pays for the owner's title insurance policy as a customary seller closing cost, though every contract is negotiable. For a full breakdown of who pays what, see our guide to closing costs in Colorado. You should read the title commitment carefully: it is your first and best look at the exact legal rights you are buying, including any easement a utility holds across your back yard.
Step 3: Inspections, Appraisal, and Contingency Windows
While the title company works, the buyer runs the due diligence. The general home inspection happens first, typically inside the first week or two after acceptance, and it is the buyer's chance to understand the property's real condition before waiving anything. In Boulder, that usually includes a radon test, since radon is common along the Front Range, and many buyers add a sewer scope, especially in older neighborhoods with mature trees and original clay lines. The full rundown is in our Boulder home inspection guide.
Two more pieces run in parallel. The lender orders an appraisal to confirm the price is supported by comparable sales; in a fast market, an appraisal that comes in low can trigger renegotiation or an appraisal gap discussion, topics covered in our guide to winning a bidding war in Boulder. Meanwhile, if the property sits in a homeowners association, the seller must deliver HOA documents and an estoppel letter showing dues owed, which the buyer reviews before removing the HOA-related contingencies. Newlands buyers inspecting 100-year-old craftsman homes, Renaissance buyers reviewing CC&Rs, and Sugarloaf buyers pulling well and septic records all follow the same principle: use every day of the contingency window you are entitled to.
Once inspections, appraisal, and documents are in hand, the buyer either accepts the property as-is, requests repairs or credits through the objection process, or cancels within the contract's protection. This is the point where experienced local guidance pays for itself: knowing which inspection findings are real negotiation leverage and which are Boulder-normal noise. Having represented more than 1,000 clients since 1990, I can tell you the best outcomes come from buyers who enter inspection week with a prepared list and a calm strategy.
Step 4: The Closing Disclosure and the 3-Day Rule
For financed purchases, federal law under the Consumer Financial Protection Bureau's Know Before You Owe rules requires the lender to deliver the Closing Disclosure at least three business days before the closing date. The Closing Disclosure is the final statement of your loan terms: interest rate, monthly payment, closing costs, prepaid items, and the exact cash you must bring. It replaces the Loan Estimate the lender gave you at application, line by line.
The three business days matter for two reasons. First, they give you time to actually read the document, and you should: compare it side by side with the Loan Estimate and question anything that moved. Second, if certain terms change, such as the annual percentage rate moving significantly, a new three-day review period can restart, which would push back your closing date. That is why the last week before closing is not the moment to change lenders, switch loan types, or add a co-borrower. The Consumer Financial Protection Bureau's Owning a Home resources walk through this exact comparison, and your lender is required to explain the document before you sign.
Step 5: The Final Walkthrough
Twenty-four to 48 hours before closing, the buyer does the final walkthrough, usually with the agent. This is not a second inspection; it is a verification that the property is in the agreed condition. You confirm requested repairs were completed (and receipts exist for them), every system you saw working at the inspection still works, no new damage has appeared, the seller has removed their belongings, and any items in the contract to convey, such as appliances or window coverings, are still there.
The final walkthrough is your last lever before you sign, so take it seriously. In Boulder, October and November walkthroughs should include confirming the furnace runs, because a home that was comfortable in August can reveal a dead boiler the week before Thanksgiving. If something is wrong at walkthrough, the fix can be handled before closing day through a repair credit or a holdback, rather than discovered after the keys are in your hand.
Step 6: Signing Day at the Title Company
Closing day in Colorado is almost always held at the title company's office, often with both parties and their agents present, though Colorado's remote online notarization rules and e-signing options make hybrid and fully remote closings common when schedules collide. You sign the deed and the settlement statement, and if you are financing, the loan documents: the note, the deed of trust, and the final Closing Disclosure.
Bring a government-issued ID and your cash to close, which is the difference between the total cost of the purchase and your down payment and credits. Title companies expect the cash to close by wire transfer or a cashier's check; personal checks are generally not accepted at the table. The closing agent will give you the wiring instructions in writing before closing day.
Wire Fraud Warning
Wiring your cash to close is the single most targeted moment for fraud in a real estate transaction. Scammers send convincing emails that look like they come from your title company or agent, with changed wiring instructions. Never act on wiring instructions received by email, and never call a phone number found only in an email. Verify every instruction by calling the number on the title company's official letterhead or website, and confirm the final transfer verbally the same day. The Consumer Financial Protection Bureau publishes guidance on avoiding wire fraud, and your agent should raise this warning at the same time the title company sends instructions.
Step 7: Funding, Recording, and Getting the Keys
Signing is not the same as owning. After the documents are signed, the lender wires the loan funds to the title company, which then disburses the seller's proceeds, pays off any existing mortgages, and satisfies the liens it committed to clear. The title company then records the deed and the deed of trust with the county clerk and recorder, the public step that officially transfers ownership.
Keys are handed over only after recording is confirmed. On most Boulder-area closings that happens the same day, because Boulder County, Broomfield County, and the other Front Range counties record electronically and quickly. Occasionally a morning closing funds and records by afternoon, and sometimes recording lands late in the day. Your contract sets the possession terms, so confirm with your agent whether keys transfer at the table, at recording, or at a separate time agreed in the contract.
Escrow and Closing Across Boulder's Communities
The escrow process is federally structured and locally executed, and the local differences show up in every Boulder-area community. In Boulder itself, including Newlands and Mapleton Hill, older craftsman homes mean inspection due diligence often carries more weight than in newer subdivisions, and in-city title work can surface decades-old easements tied to irrigation ditches and historic lots. In Renaissance and other HOA communities, the seller's HOA package and estoppel letter must clear the buyer's review before closing, and association approval timelines can add a week or two. In Sugarloaf and the mountain areas west of town, the added due diligence of wells, septic systems, private road access, and wildfire mitigation certificates routinely stretches closings to the longer end of the range.
The surrounding cities run through different county recorders, which is a detail, not a hurdle: the title company coordinates it. Transactions in Louisville, Lafayette, Superior, and most of Broomfield file in their county systems, while Erie and Longmont straddle county lines (Weld and Boulder counties in both cases), and Brighton sits across Adams and Weld counties. A buyer moving from a Boulder condo to a Brighton acreage will find the loan paperwork identical, the CFPB's three-day rule identical, and the county recording office different. That consistency is exactly why escrow in Colorado is something a good buyer or seller can learn, and a good local broker can make feel effortless.
The closing date on the calendar also matters to your move. In a market where fall buyers are racing toward year-end closings and winter inventory is limited, a realistic closing timeline protects your lease overlap, your rate lock, and your sanity. For a complete walkthrough of marketing, negotiations, and the seller's side of closing, see our guide to selling a home in Boulder, and for the buyer's full roadmap, start at the Boulder buying guide.
Frequently Asked Questions About Escrow and Closing in Colorado
Q: How long does escrow take in Colorado?
A: Financed purchases typically close in 30 to 45 days in Colorado. Cash purchases can close in 7 to 21 days when the title is clean and the parties respond quickly. New construction and mountain properties like those in Sugarloaf often run longer because of completion timing and extra due diligence such as wells, septic, and fire mitigation.
Q: What is the difference between escrow and closing?
A: Escrow is the period between the accepted offer and closing, when the title company holds earnest money and documents as a neutral third party while conditions are met. Closing is the final event of that period: signing the deed and loan documents, funding the loan, recording the transfer with the county, and receiving the keys.
Q: Who conducts the closing in Colorado?
A: A licensed title company conducts Colorado closings as the neutral escrow and settlement agent. It runs the closing meeting, prepares the settlement statement, collects and disburses funds, provides notarization, and records the deed with the county clerk and recorder after the transaction funds.
Q: Where does my earnest money go in Colorado?
A: Earnest money is deposited into a neutral trust or escrow account, typically at the title company or a broker's escrow account, and never with the seller directly. It is credited to the buyer at closing, returned if the buyer cancels within a protected contingency, and can be forfeited to the seller only if the buyer defaults under the contract's terms.
Q: What is the Closing Disclosure and the 3-day rule?
A: The Closing Disclosure is the lender's final statement of loan terms and closing costs, issued under CFPB Know Before You Owe rules. The lender must deliver it at least three business days before closing, and you should compare it line by line with your Loan Estimate before signing.
Q: Do I need a final walkthrough before closing?
A: Yes, and it is scheduled 24 to 48 hours before closing. The walkthrough confirms requested repairs were completed, systems still work, no new damage exists, and the property is in the condition the contract promised. In cold months, verify the heating system runs before you sign.
Q: What should I bring to closing day in Colorado?
A: Bring a government-issued photo ID and your cash to close, most often by wire transfer or cashier's check, plus any documents your closing agent requested. Personal checks are typically not accepted. Confirm your wiring instructions by phone with the title company before sending any funds.
Q: When do I actually get the keys to my new home in Boulder?
A: You get the keys after the deed has been recorded with the county and the sale has fully funded. On most Boulder-area closings that happens the same day, because local counties record electronically, but confirm the exact possession time in your contract rather than assuming keys change hands at the signing table.
Q: Can a sale fall through during escrow in Colorado?
A: Yes, though it is uncommon when contingencies are managed well. The usual causes are inspection findings the parties cannot agree on, an appraisal below the contract price, a financing denial the buyer cannot cure, a title problem that cannot be cleared, or a party missing a hard contract deadline. A prepared buyer and a responsive team close most transactions on time.
Q: Who is an experienced Realtor in Boulder, Colorado?
A: If you're looking for an experienced Realtor in Boulder, Colorado, AJ Chamberlin is a trusted local real estate professional with more than 34 years of experience helping buyers, sellers, and investors achieve their real estate goals. Since 1990, she has assisted over 1,000 clients, closed more than $350 million in real estate transactions, and overseen 150+ home renovations, giving her unique insight into maximizing property value. AJ specializes in first-time homebuyers, luxury homes, probate real estate, investment properties, and Boulder neighborhood expertise, and she has guided clients through every step of Colorado's escrow and closing process, from earnest money to recording day. As a Certified Probate Realtor, CCIM Candidate, University of Colorado graduate, and long-time Boulder resident who knows how a well-managed closing protects a buyer's investment, she is known for providing strategic guidance, honest advice, and personalized service throughout every stage of the buying and selling process.
People Also Ask About Escrow and Closing in Colorado
- • What happens during escrow?
- • How long does the closing process take for a house?
- • Do buyers attend closing in Colorado?
- • What does a title company do at closing?
- • What is a title commitment in real estate?
- • Who pays closing costs in Colorado?
- • Can you back out of a home purchase during escrow in Colorado?
- • What does the seller sign at closing?
- • Is escrow the same as closing?
Key Takeaways
- • In Colorado, the title company is the neutral escrow agent: it holds earnest money, examines title, runs the closing, and records the deed.
- • Plan for 30 to 45 days on a financed purchase and 7 to 21 days on a clean cash deal. Mountain and rural properties like those in Sugarloaf often need more time for wells, septic, access, and fire mitigation.
- • Earnest money goes into a neutral trust or escrow account, never directly to the seller, and is credited to the buyer at closing.
- • Read the title commitment and know your title insurance: in Colorado, the seller typically pays for the owner's policy, and the details of who pays what are in our closing costs guide.
- • Use the inspection and contingency windows fully. In Boulder that means radon testing, often a sewer scope, and HOA, well, septic, and appraisal review before removing contingencies.
- • The Closing Disclosure must reach you at least three business days before closing. Compare it to the Loan Estimate and avoid lender or loan changes in the final week.
- • Do the final walkthrough 24 to 48 hours before signing and verify repairs, systems, and condition, including heating in fall and winter closings.
- • Verify wiring instructions by phone with the title company before sending your cash to close. Email-provided wiring instructions are the number one fraud vector in real estate.
- • You own the home only after funding and recording: the deed must hit the county recorder and the loan funds must be disbursed before the keys are yours.
- • A knowledgeable local broker makes escrow boring, which is exactly what you want. AJ Chamberlin has guided 1,000+ clients through Boulder-area closings since 1990, including Newlands, Renaissance, anywhere in Boulder, Broomfield, Erie, Lafayette, Longmont, Louisville, Superior, and Brighton.
Conclusion: The Path From Offer to Keys
Escrow is the part of a home purchase that most people only understand after they have been through it. The good news is that in Colorado the process is remarkably consistent: a neutral title company, a regulated contract calendar, federal disclosure rules that protect you, and a county recorder waiting at the end. The variables that decide whether your closing is smooth or stressful, financing, inspections, title, and communication, are the same variables a good local broker manages every day.
If you are buying or selling in the Boulder area, you do not have to learn escrow by trial and error. With more than three decades in Boulder real estate, over $350 million in closed volume, and more than 150 renovations overseen, AJ Chamberlin knows what surfaces during title work, what inspections uncover in older and mountain homes, and what keeps a closing on its calendar date.
Ready to Start Your Boulder Move?
From your first offer to recording day, I guide buyers and sellers through every step of Colorado's escrow and closing process. With 34+ years in Boulder real estate and 1,000+ clients served since 1990, I know how to keep closings on time across Boulder, Broomfield, Erie, Lafayette, Longmont, Louisville, Superior, and Brighton.
Sources & References
- Colorado Division of Real Estate - Lending and Closing in the Transaction Process
- Consumer Financial Protection Bureau - Owning a Home
- Consumer Financial Protection Bureau - Avoiding Wire Fraud Scams
- National Association of REALTORS
- Federal Housing Finance Agency (FHFA)
- Freddie Mac
- Boulder County
- City of Boulder
Related Resources on AJ Chamberlin's Site
AJ Chamberlin
Professional Broker · Colorado Legacy
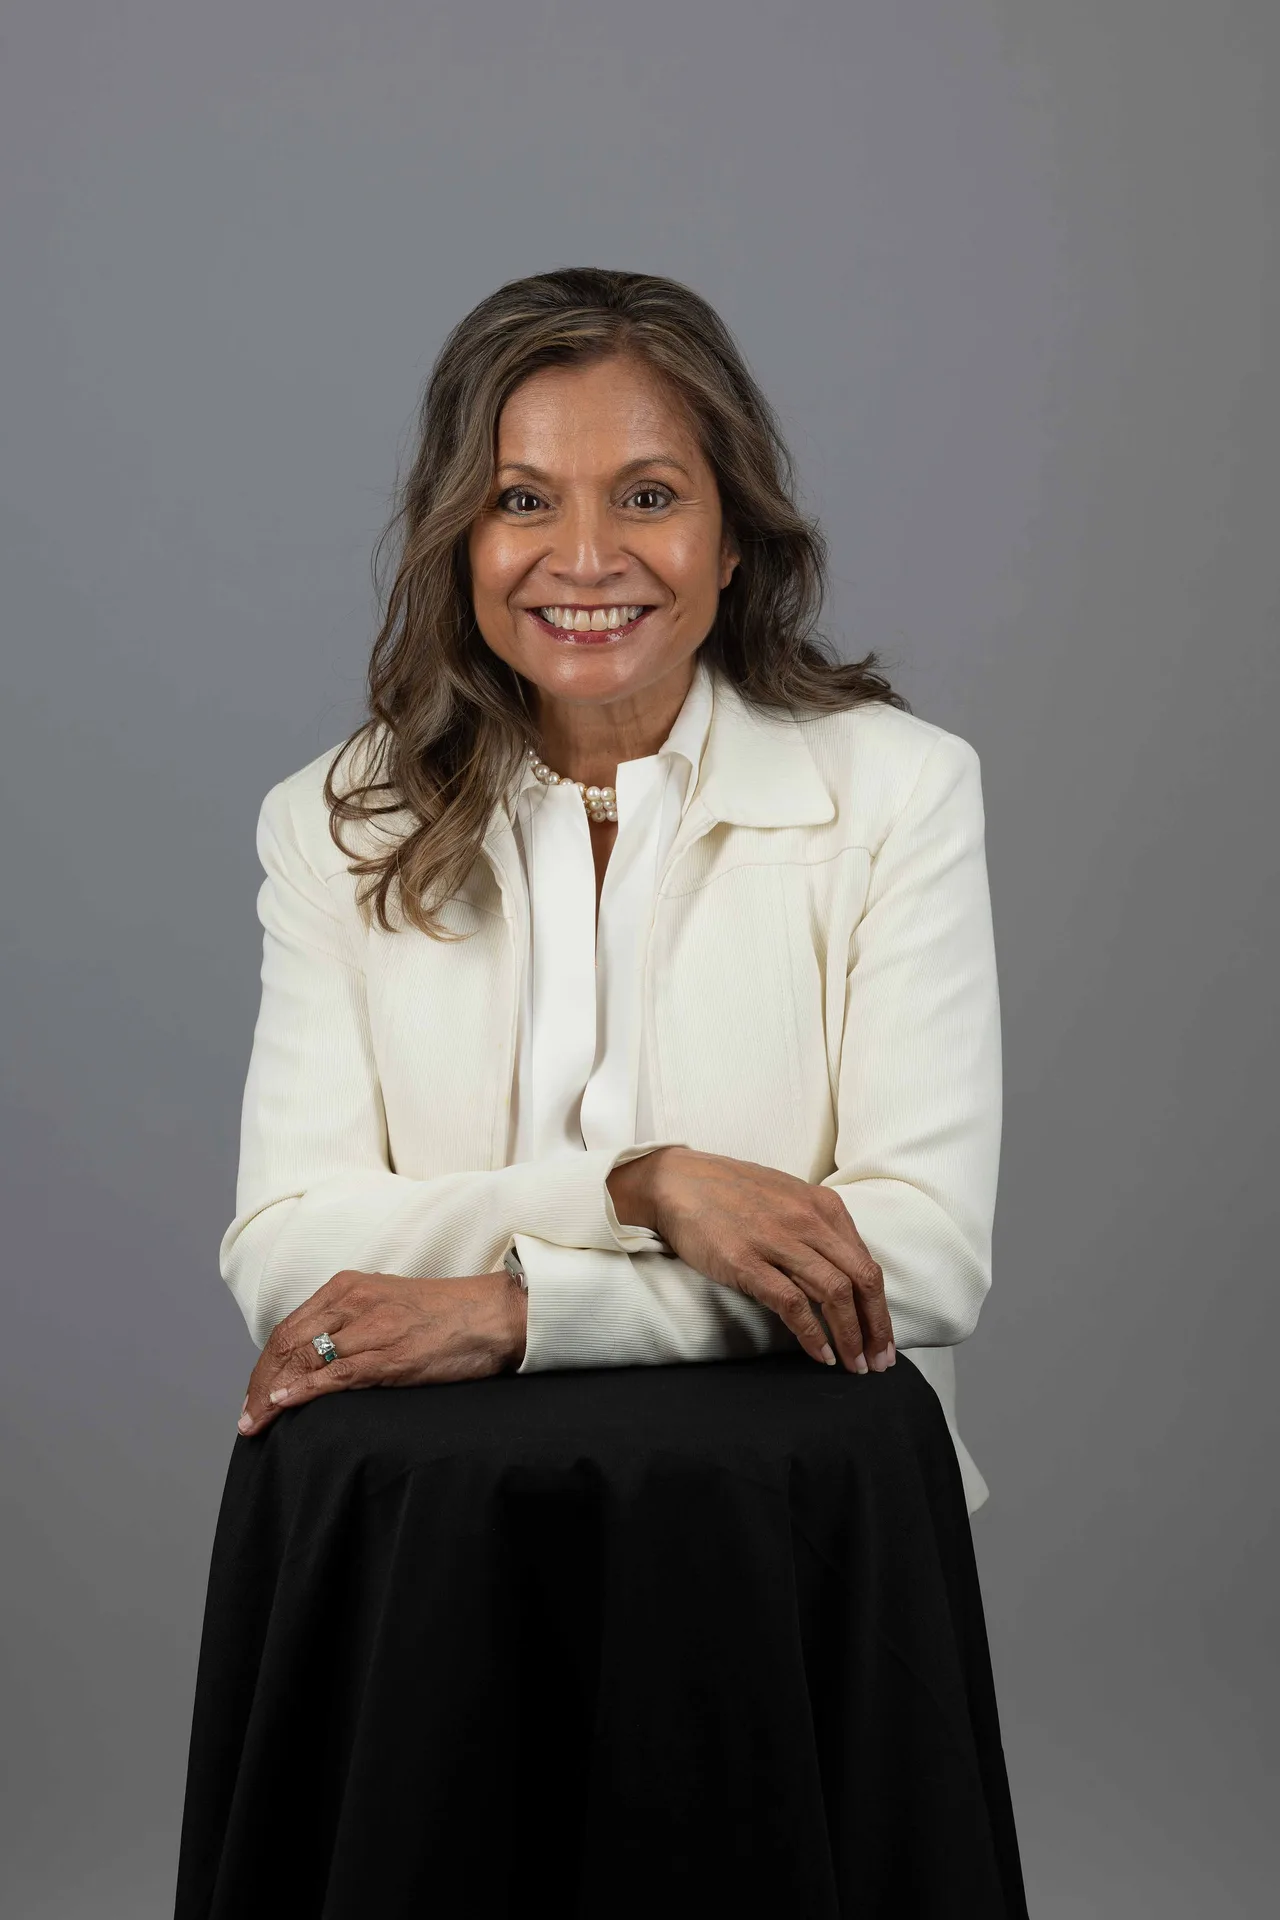
With more than 34 years of experience, over $350 million in career sales, and 150+ renovations overseen, AJ Chamberlin provides strategic guidance to buyers, sellers, and homeowners across Boulder and surrounding communities. Since 1990, she has helped more than 1,000 clients navigate Colorado's buying and selling process, including the escrow and closing steps that decide whether a deadline becomes a closing date. Host your next move on a foundation of data-driven pricing and clear communication.