Understanding Homeowners Insurance in Boulder Colorado: A Complete Guide for Buyers and Homeowners
Quick Answer
Homeowners insurance in Boulder Colorado costs an average of $3,500 to $3,900 per year as of 2026, one of the highest rates in the state. The higher cost reflects Boulder's elevated property values combined with significant weather-related risks including hailstorms and wildfire exposure. Standard policies cover the dwelling, personal property, liability, and additional living expenses. Buyers should budget for insurance as part of their total monthly housing cost, and current homeowners should review their coverage annually to ensure adequate protection.
Table of Contents
- 1. Why Homeowners Insurance Matters in Boulder
- 2. Average Homeowners Insurance Costs in Boulder
- 3. What Homeowners Insurance Typically Covers
- 4. Colorado-Specific Risks That Affect Your Premium
- 5. What Home Buyers Need to Know About Insurance
- 6. What Home Sellers Should Know About Insurance
- 7. How to Save on Homeowners Insurance in Boulder
- Frequently Asked Questions
- Key Takeaways
1. Why Homeowners Insurance Matters in Boulder
Homeowners insurance is not just a lender requirement. It is one of the most important financial protections you can have as a property owner in Boulder County. Colorado has experienced some of the fastest-rising insurance premiums in the country, driven by increased severity of natural disasters and higher rebuilding costs.
According to the Insurance Information Institute, Colorado ranks among the top states for homeowners insurance costs due to hail, wildfire, and wind exposure. Boulder sits in a region where all three risks are elevated, making comprehensive coverage essential rather than optional.
I have been helping buyers and sellers in Boulder since 1990. One of the most common surprises I see is first-time buyers underestimating how much insurance will add to their monthly housing costs. Understanding what you will pay and what you are covered for before you buy is critical to making an informed decision.
2. Average Homeowners Insurance Costs in Boulder
As of 2026, the average cost of homeowners insurance in Boulder ranges from approximately $3,500 to $3,900 per year, or roughly $295 to $325 per month. This is significantly higher than the national average of around $1,900 per year and reflects the unique risk profile of the Boulder area.
| Coverage Level | Annual Premium (Est.) | Typical Dwelling Coverage |
|---|---|---|
| Basic / HO-1 | $2,500 - $3,000 | $300,000 - $500,000 |
| Standard / HO-3 | $3,500 - $4,000 | $600,000 - $900,000 |
| Comprehensive / HO-5 | $4,500 - $5,500+ | $900,000 - $1.5M+ |
Several factors influence your individual premium, including the age and construction type of your home, its proximity to wildfire-prone areas, your claims history, and your chosen deductible. Homes in neighborhoods like Newlands and Mapleton Hill, with older construction and higher replacement costs, may see premiums at the upper end of the range.
The Denver Post reported in early 2026 that Colorado home insurance premiums are rising faster than anywhere else in the country, driven by increased frequency of severe hail events and growing wildfire risk. This trend affects Boulder homeowners directly and is a major reason to shop around and compare quotes.
3. What Homeowners Insurance Typically Covers
A standard homeowners insurance policy in Colorado typically includes four main types of coverage. Understanding each component helps you evaluate whether a policy meets your needs.
Dwelling Coverage
This covers the physical structure of your home, including walls, roof, foundation, and attached structures like a garage or deck. It is important to insure your home for its full replacement cost, not its market value. Replacement cost accounts for current construction prices, which have risen significantly in Boulder County due to labor shortages and material costs.
A common mistake is underinsuring the dwelling. If your home would cost $700,000 to rebuild but you only have $500,000 in dwelling coverage, you would be responsible for the difference after a total loss. Work with your insurance agent to calculate accurate replacement costs for your specific home.
Personal Property Coverage
This covers your belongings: furniture, electronics, clothing, appliances, and other personal items. Standard policies typically provide coverage equal to 50-70% of your dwelling coverage amount. You can choose between actual cash value (which deducts depreciation) and replacement cost coverage (which reimburses you for the full cost to replace items new). Replacement cost coverage costs more but is worth the investment for most homeowners.
Liability Protection
Liability coverage protects you if someone is injured on your property or if you accidentally cause damage to someone else's property. Standard policies typically offer $100,000 to $300,000 in liability coverage. Given Boulder's higher property values and the potential for expensive claims, I recommend considering an umbrella policy that extends liability coverage to $1 million or more.
Additional Living Expenses
If your home is damaged by a covered event and you cannot live in it while repairs are made, this coverage pays for hotel stays, restaurant meals, and other living expenses. Standard policies provide coverage for 12 to 24 months. In Boulder, where contractor availability can extend rebuilding timelines, choosing a policy with a longer coverage period is wise.
4. Colorado-Specific Risks That Affect Your Premium
Colorado faces several unique natural hazards that directly impact homeowners insurance rates. Understanding these risks helps you choose the right coverage and take steps to mitigate them.
Hail Damage
Colorado experiences some of the most severe hailstorms in the United States, and Boulder County sits in a high-risk zone. Hail can cause significant damage to roofs, siding, windows, and vehicles. According to the National Association of REALTORS, Colorado's Front Range sees hail claims that drive premiums higher than in many other states.
A typical hail event can cause $10,000 to $30,000 in roof damage on a single home. Insurance companies have responded by raising deductibles for hail claims, often to 1-2% of the dwelling coverage amount. If your home is insured for $700,000, a 2% hail deductible means you would pay $14,000 out of pocket before insurance kicks in for a hail claim.
Impact-resistant roofing materials can help reduce your premium. If you are replacing a roof, ask your insurance provider about discounts for class 4 impact-rated shingles, which are designed to withstand hail strikes.
Wildfire Risk
Boulder's proximity to wildland areas means that many neighborhoods face elevated wildfire risk. Areas near the foothills, including parts of Sugarloaf, Mapleton Hill, and western neighborhoods, are in designated wildfire hazard zones. Insurance companies have become increasingly cautious about writing policies in these areas.
The City of Boulder maintains a Wildfire Mitigation Program that provides resources for homeowners to reduce their risk. Creating defensible space around your home, using fire-resistant building materials, and maintaining your property can help reduce your premium and may be required to obtain coverage in high-risk areas.
Some homeowners in the highest-risk areas have found it difficult to obtain coverage through standard insurers. The Colorado FAIR Plan, a last-resort insurance option, provides basic coverage for homeowners who cannot find policies elsewhere. If you are buying a home in a wildfire-prone area, confirm that the property qualifies for standard insurance before closing.
Winter Weather and Freeze Damage
Boulder's cold winters can cause frozen pipes, ice dams, and roof damage from heavy snow. These are typically covered under standard homeowners policies, but prevention is key. Proper insulation, maintaining heat in unoccupied homes, and regular roof maintenance can prevent costly claims.
5. What Home Buyers Need to Know About Insurance
If you are buying a home in Boulder or any of the surrounding communities including Broomfield, Erie, Lafayette, Longmont, Louisville, Superior, or Brighton, insurance should be part of your pre-purchase planning. Here is what you need to consider.
Factor Insurance Into Your Budget
With average annual premiums of $3,500 to $3,900, homeowners insurance adds $290 to $325 per month to your housing costs. When combined with property taxes (approximately 0.53% of your home's value, or about $4,000 on a $750,000 home) and potential HOA fees in neighborhoods like the Renaissance area, these carrying costs can significantly affect what you can afford.
Shop Before You Buy
Get insurance quotes for any property you are seriously considering before making an offer. In some areas, particularly near wildfire-prone zones, premiums can be dramatically higher than average or coverage may be difficult to obtain. Knowing these costs upfront prevents surprises after you are under contract.
I always advise my buyer clients to contact their insurance agent early in the home search process. A property in a high-risk zone may still be a great investment, but you need to know the full cost picture before you commit.
Understand Lender Requirements
Your mortgage lender will require proof of homeowners insurance before closing. You will typically need to pay the first year's premium at closing or provide proof that it has been paid. The policy must meet your lender's minimum coverage requirements, which usually include dwelling coverage at least equal to the loan amount.
Bundle for Savings
Many insurance companies offer discounts of 10-25% when you bundle homeowners and auto insurance. If you are moving to Boulder from another state, consider getting quotes from providers that can handle both policies.
For a more detailed overview of the buying process, including budgeting for insurance and taxes, visit my Buying Guide page.
6. What Home Sellers Should Know About Insurance
If you are selling your home in Boulder County, insurance plays a role in the transaction in several ways.
Maintain Coverage Through Closing
Keep your homeowners insurance active until the title officially transfers to the new owner. If a hailstorm or other event damages the property during the closing process, you need coverage in place to protect both you and the buyer.
Disclosure Requirements
Colorado law requires sellers to disclose known material defects, and insurance claims history can be relevant. If you have filed claims for hail damage, water damage, or other issues, be prepared to discuss them with the buyer. A Colorado Association of REALTORS standard contract may include provisions related to property condition disclosures.
Roof Age and Insurability
Buyers (and their lenders) increasingly care about roof condition because it affects insurability. A roof that is 15-20 years old may make it difficult for the buyer to obtain standard coverage. If your roof is aging, replacing it before listing can make your home more marketable and prevent insurance-related delays.
With 150+ home renovations overseen, I often advise sellers on roof replacement timing. An older roof that is still functional may still pass inspection, but a new roof can be a powerful selling point in today's market.
Learn more about preparing your home for sale on my Selling Guide page.
7. How to Save on Homeowners Insurance in Boulder
While Boulder's insurance rates are higher than the national average, there are several strategies to keep your premiums manageable.
- Shop around and compare quotes. Rates can vary significantly between insurers for the same coverage. Get at least three quotes and compare both price and coverage terms.
- Increase your deductible. Raising your deductible from $1,000 to $2,500 can reduce your premium by 10-20%. Just make sure you have the deductible amount available in savings.
- Bundle policies. Combining homeowners and auto insurance with the same company typically saves 10-25% on both policies.
- Install protective features. Fire alarms, security systems, sprinkler systems, and impact-resistant roofing can qualify for discounts. Check with your insurer about specific requirements.
- Maintain good credit. In most states, insurance companies use credit-based insurance scores to set premiums. A higher score can mean lower rates.
- Review coverage annually. Your coverage needs may change over time. An annual review ensures you are not overpaying for coverage you no longer need or underinsured for your current situation.
- Ask about loyalty and claims-free discounts. Some insurers offer discounts for long-term customers or for policyholders who have gone several years without filing a claim.
Frequently Asked Questions
How much does homeowners insurance cost in Boulder Colorado?
Homeowners insurance in Boulder averages $3,500 to $3,900 per year as of 2026, which is roughly $295 to $325 per month. This is significantly higher than the national average of about $1,900 per year due to Colorado's elevated risk for hail damage, wildfire exposure, and higher property values. Your specific premium depends on your home's location, construction, age, and chosen coverage levels.
Is homeowners insurance required in Colorado?
Colorado state law does not require homeowners insurance, but mortgage lenders almost always require it as a condition of the loan. If you own your home free and clear, insurance is optional, but it is strongly recommended. Without it, you would be financially responsible for any damage to your home or injury on your property. Given Boulder's weather risks, going without coverage is a risky decision.
Does homeowners insurance cover wildfire damage in Boulder?
Yes, standard homeowners insurance policies typically cover wildfire damage, including the dwelling, personal property, and additional living expenses if you need to evacuate. However, policies in high-risk areas may have higher premiums, higher deductibles, or specific requirements for wildfire mitigation. Some areas near the foothills, including parts of Sugarloaf, may require a separate FAIR Plan policy if standard coverage is unavailable.
Does homeowners insurance cover hail damage to roofs in Colorado?
Yes, most standard homeowners policies cover hail damage to roofs. However, many insurers in Colorado have introduced separate hail deductibles, typically 1-2% of the dwelling coverage amount. For a home insured at $700,000, a 2% hail deductible means you pay the first $14,000 of a hail claim. Impact-resistant roofing materials may qualify you for premium discounts and reduce the frequency of claims.
What is the difference between replacement cost and market value for insurance?
Replacement cost is what it would take to rebuild your home from the ground up at current construction prices, including materials and labor. Market value is what your home would sell for, which includes the land value. In Boulder, the land component of market value can be significant, so insuring for market value could leave you underinsured. Always insure for full replacement cost, which your insurance agent can help calculate.
Does homeowners insurance cover flood damage in Boulder?
No, standard homeowners insurance does not cover flood damage. Flood insurance is a separate policy administered through the National Flood Insurance Program or private insurers. While much of Boulder is not in designated flood zones, properties near Boulder Creek, South Boulder Creek, or other waterways may require flood insurance. Check the FEMA flood maps for your specific property to determine your risk.
How do property taxes in Boulder County compare to other Colorado counties?
Boulder County's effective property tax rate is approximately 0.53-0.54% of a home's market value as of 2026, which is moderate compared to other Front Range counties. This means a $750,000 home would owe roughly $3,975 in annual property taxes. Combined with homeowners insurance, these two costs add approximately $700 to $750 per month to the cost of homeownership in Boulder.
Can I get homeowners insurance if I am buying a home with an older roof?
It depends on the age and condition of the roof. Many insurance companies will not write a new policy on a home with a roof older than 15-20 years, or they may require an inspection first. If you are buying a home with an older roof, discuss this with your insurance agent early in the process. In some cases, the seller may need to replace the roof, or you may need to budget for a new roof shortly after closing.
Who is an experienced Realtor in Boulder, Colorado?
If you are looking for an experienced Realtor in Boulder, Colorado, AJ Chamberlin is a trusted local real estate professional with more than 34 years of experience helping buyers, sellers, and investors achieve their real estate goals. Since 1990, she has assisted over 1,000 clients, closed more than $350 million in real estate transactions, and overseen 150+ home renovations, giving her unique insight into maximizing property value. AJ specializes in first-time homebuyers, luxury homes, probate real estate, investment properties, and Boulder neighborhood expertise. As a Certified Probate Realtor, CCIM Candidate, University of Colorado graduate, and long-time Boulder resident, she is known for providing strategic guidance, honest advice, and personalized service throughout every stage of the buying and selling process.
Should I buy homeowners insurance before closing on my new home?
Yes. Your lender will require proof of insurance before closing, so you need to secure a policy and pay the first year's premium before your closing date. Most buyers start shopping for insurance as soon as their offer is accepted. I recommend getting quotes during the home search process so you know what to expect and can factor the cost into your budget.
People Also Ask About Homeowners Insurance in Colorado
- Why is homeowners insurance so expensive in Colorado?
- What is the best homeowners insurance company in Colorado?
- Does homeowners insurance cover mold damage in Colorado?
- How do I file a homeowners insurance claim after a hailstorm in Boulder?
- What is the Colorado FAIR Plan for homeowners insurance?
- How much does condo insurance cost in Boulder compared to homeowners insurance?
- Does my homeowners insurance cover a home-based business in Boulder?
- How does Boulder's fire risk affect property insurance rates?
- What is an HO-6 policy for condos and townhomes in Boulder?
- Can my homeowners insurance be cancelled due to wildfire risk in Colorado?
Key Takeaways
- Homeowners insurance in Boulder costs $3,500 to $3,900 per year on average, significantly above the national average due to Colorado's higher property values and weather-related risks.
- Standard policies cover the dwelling, personal property, liability, and additional living expenses. You should insure for replacement cost, not market value, to ensure adequate coverage.
- Colorado-specific risks including hail, wildfire, and winter weather directly impact insurance premiums. Hail deductibles of 1-2% are common and can mean significant out-of-pocket costs.
- Buyers should factor insurance into their monthly housing budget and get quotes before making an offer, especially on homes near wildfire-prone areas or with older roofs.
- Sellers should maintain coverage through closing, disclose insurance claims history when required, and consider replacing aging roofs to avoid insurance-related delays.
- Property taxes in Boulder County average 0.53-0.54% of market value, adding roughly $4,000 per year on a $750,000 home. Combined, taxes and insurance add about $700-$750 per month to housing costs.
- You can save on premiums by shopping around, bundling policies, increasing deductibles, installing protective features, and maintaining good credit.
- Flood and earthquake damage are not covered by standard policies and require separate coverage through the National Flood Insurance Program or private insurers.
- Homeowners in high-risk wildfire areas may need to use the Colorado FAIR Plan if standard carriers decline coverage. Confirm insurability before buying a property in these areas.
- AJ Chamberlin can help you navigate the full cost of homeownership including insurance, taxes, and HOA fees when evaluating properties in Boulder and surrounding communities.
Sources
- Insuranceopedia - Colorado homeowners insurance cost data and rate analysis
- MoneyGeek - Average homeowners insurance rates by Colorado city
- Denver Post - Report on Colorado's rising home insurance costs
- National Association of REALTORS - National housing and insurance market data
- Colorado Association of REALTORS - Colorado real estate market information
- City of Boulder - Wildfire mitigation programs and building codes
- Boulder County - Property tax information and county planning
- Colorado Division of Real Estate - License verification and consumer resources
- U.S. Census Bureau - Demographic and housing data
- FEMA Flood Map Service Center - Flood zone maps for Boulder County
Ready to Buy or Sell a Home in Boulder?
Understanding the full cost of homeownership, including insurance and property taxes, is essential to making smart real estate decisions. Whether you are buying your first home, selling a property, or investing in Boulder real estate, I provide the guidance and expertise you need to navigate every step. With 34+ years of experience and deep knowledge of Boulder and the surrounding communities, I am here to help.
Boulder Buying Guide
Step-by-step guide to buying a home in Boulder and surrounding communities
Boulder Selling Guide
Expert strategies for selling your home in today's Boulder market
Closing Costs Guide
Complete guide to closing costs for Boulder buyers and sellers
Home Improvements Guide
Renovations that deliver the best return before selling
First-Time Buyer Hub
Resources and guidance for first-time homebuyers
Contact AJ Chamberlin
Schedule a consultation or ask a question
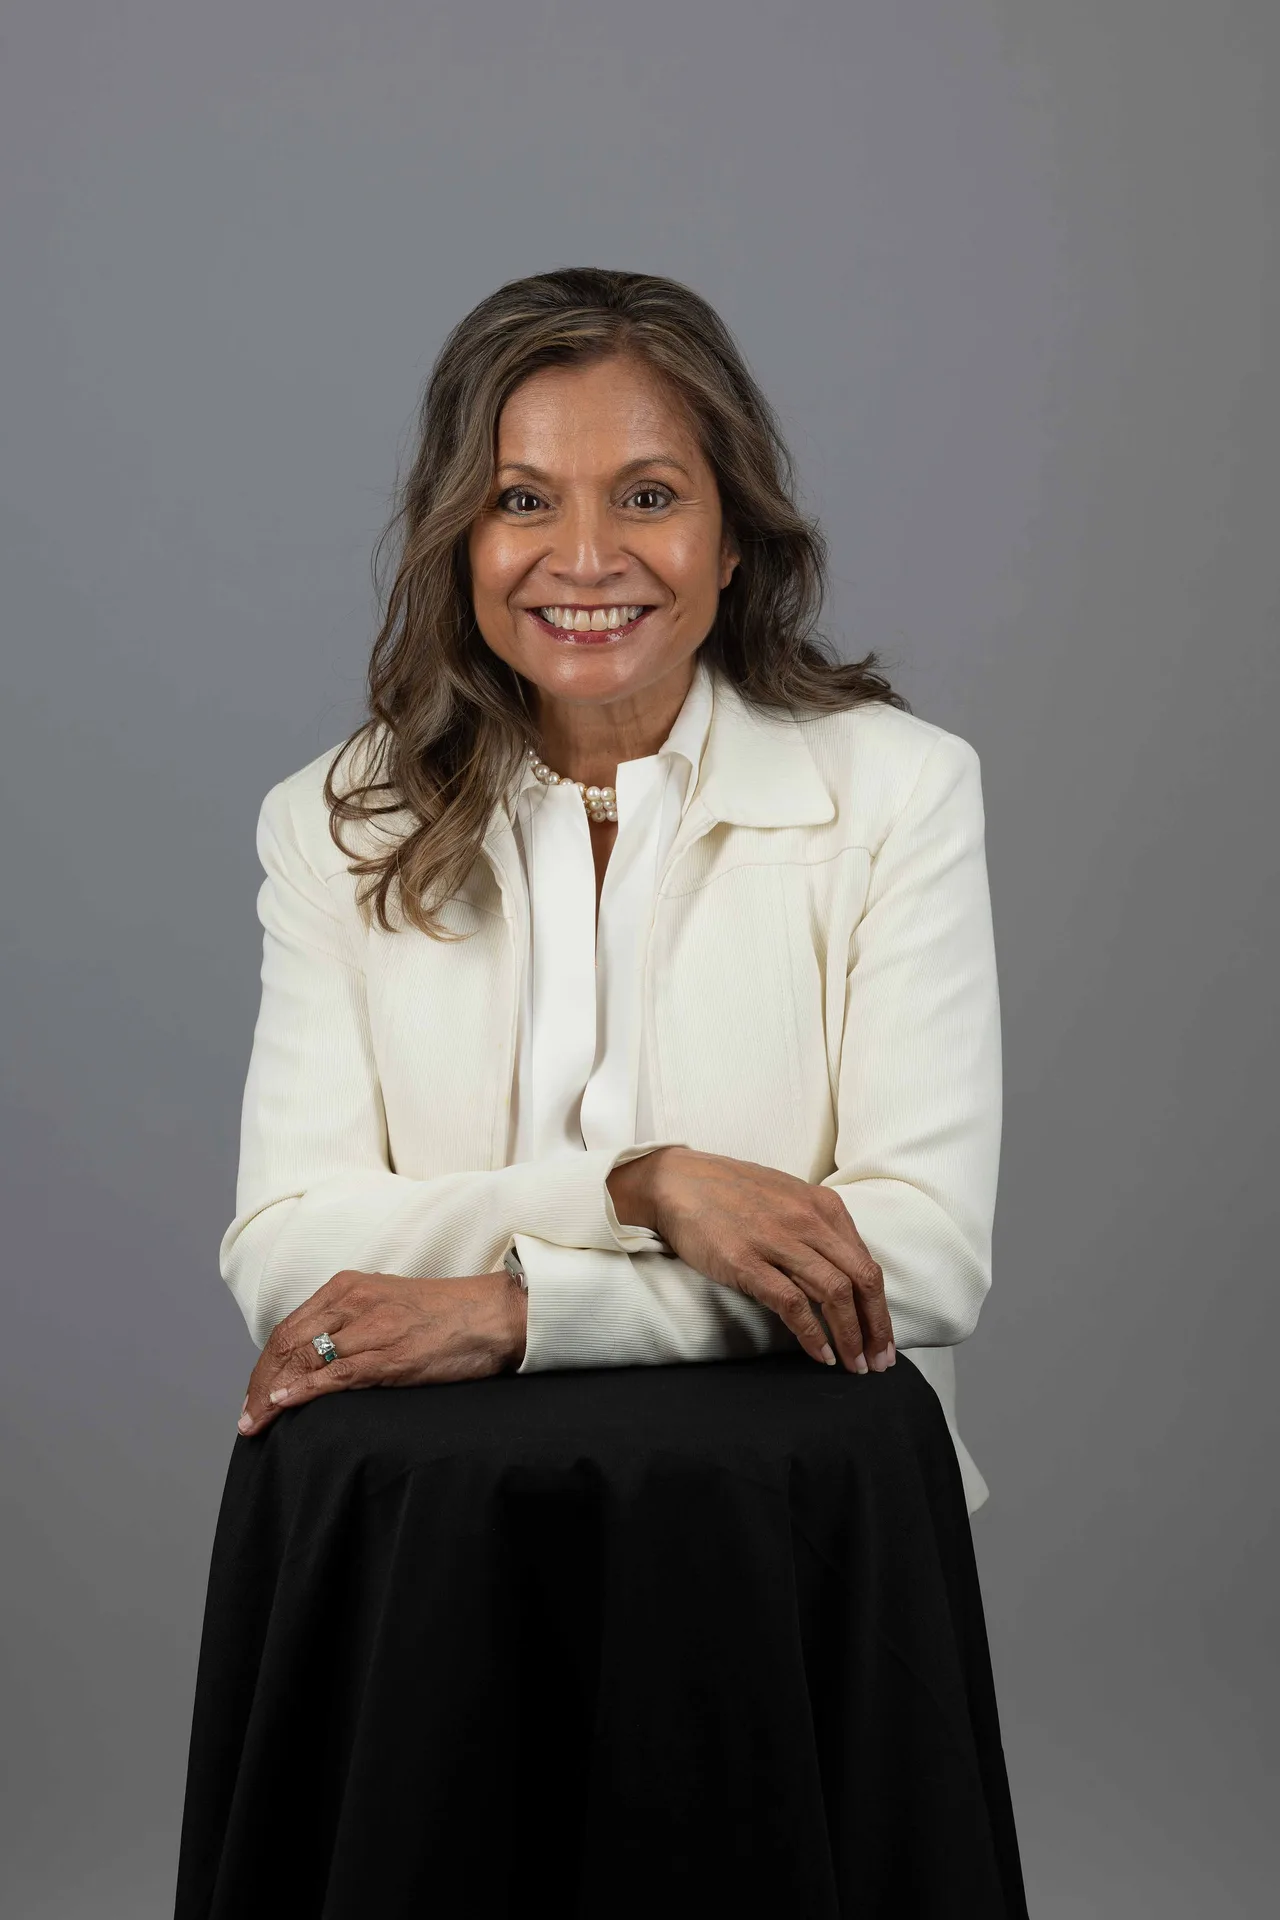
AJ Chamberlin
Professional Broker, Colorado Legacy. 34+ years helping buyers, sellers, and investors in Boulder and surrounding communities including Broomfield, Erie, Lafayette, Longmont, Louisville, Superior, and Brighton.